

Mercado Pago: cuenta digital
by Mercado Libre
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 100.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
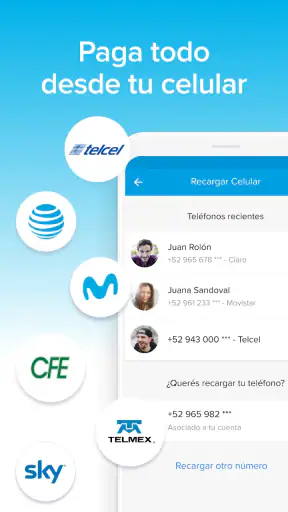
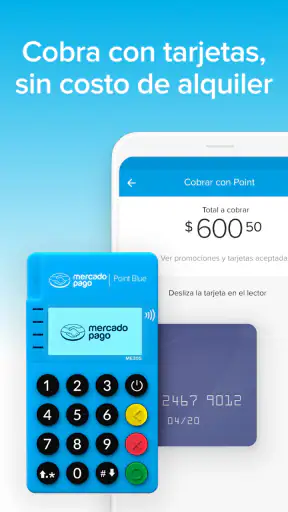
 Analysis by Getfullapps
I spent time using Mercado Pago: cuenta digital as a finance app rather than treating it as only a way to scan a payment code. My overall impression is that it brings several everyday money tasks into one place: paying with a QR code, managing a line of credit, using a card, and handling a digital account. That combination explains why it has reached over 100 million installs and holds a 4.8 average from around 14 million ratings. It is free, aimed at Everyone, and developed by Mercado Libre.
What matters to me, though, is not just how many people use it. A financial app has to be understandable when I am in a hurry, usable in different environments, and clear enough that I do not make an expensive mistake. I looked at it through that practical lens, paying particular attention to readability, navigation, motor and sensory needs, and the situations in which a phone-based account is either convenient or frustrating.
How the app feels to navigate and read
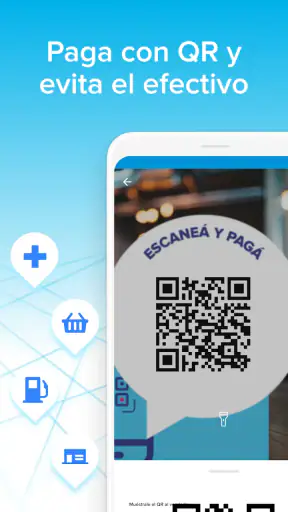
The main strength is concentration. Instead of switching between a shopping app, a separate wallet, and a banking application, I can reach several money-related actions from the same ecosystem. The QR payment flow is especially direct: when a merchant accepts that method, the phone becomes the payment tool, and I do not need to handle cash or search for a physical card.
That simplicity is useful for someone who already understands digital payments. A new user may need more time, because an account, a card, credit options, and payment tools can appear as related parts of one service even though they involve different decisions. I would not encourage anyone to activate or use credit casually just because it sits beside ordinary payment functions. The convenience of one dashboard can also make financial products feel closer than they really are.
I found the app most comfortable when I approached it with one task in mind. Opening it to pay is different from opening it to inspect account activity or consider a credit option. Deciding beforehand what I want to do reduces visual and mental clutter. This is a small habit, but it is one of my most useful recommendations for people who find finance interfaces tiring.
For readers with low vision, the practical question is whether the phone itself can make the interface easier to see. Larger system text, stronger display contrast, and a clean screen environment can help, although the result depends on the device and operating system. I would test the essential actions—opening the account, reading an amount, confirming a payment, and finding transaction information—before relying on the app for urgent purchases.
People who are unfamiliar with financial vocabulary should slow down around words connected with credit and repayment. A QR payment and a credit transaction are not interchangeable simply because both can begin inside the same app. I prefer to read each confirmation screen fully, check the amount, and make sure I understand which balance or payment method is being used.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The app’s current version is 2.454.3, and it requires Android 6.0 or later. That makes the Android requirement relatively approachable for people who keep an older phone, but compatibility alone does not guarantee a comfortable experience. An older handset may have a smaller display, slower response, or weaker battery, all of which matter when a payment depends on a quick interaction.
Why the single-app approach helps some users
There is a real cognitive benefit in having familiar money tasks grouped together. Someone who regularly pays at local businesses, checks an account, and uses a card may prefer remembering one app instead of several. It can also reduce the need to carry cash or multiple physical items, which is helpful for people who find wallets difficult to organize.
That advantage has a limit. If the app becomes the only route to money, a forgotten passcode, a dead battery, a damaged screen, or a poor connection can turn convenience into dependence. I recommend keeping an alternative payment method available, particularly when traveling or attending an appointment where a failed digital payment would be embarrassing or disruptive.
Motor and sensory considerations in daily use
A QR payment can be easier than counting notes, entering a long card number, or passing a physical card to another person. For someone with limited dexterity, reducing the number of objects to handle may be a meaningful benefit. The phone is already in hand, and the transaction can be completed through a short sequence rather than a wallet-based routine.
At the same time, QR payments are not automatically accessible. Holding a phone steady, positioning the camera, selecting a small on-screen control, and confirming the correct amount can all be difficult for someone with tremors, reduced reach, or limited fine motor control. In a busy shop, I would rather prepare the app before reaching the counter than try to complete every step while people are waiting behind me.
A useful workaround is to use a stable grip and keep the screen at a comfortable angle, rather than stretching the wrist toward the code. If another person is helping, I would keep control of the final confirmation and personally check the recipient and amount. Assistance with positioning the phone should not mean handing over control of the financial decision.
For users with hearing loss, a visual payment flow may be preferable to one that depends on spoken instructions or audible prompts. However, the user still needs to see the confirmation clearly. I would not treat a sound, vibration, or a quick change of screen as enough evidence that a payment succeeded. The safer routine is to pause and verify the visible result and the transaction record when possible.
For blind or low-vision users, compatibility with the phone’s screen reader and magnification settings is an important personal test. I cannot responsibly promise that every control or message will behave perfectly with every assistive setting, so I would try the complete payment journey before making this the primary account. The critical test is not whether the home screen opens; it is whether the user can independently identify the amount, destination, and final status.
People with light sensitivity or sensory overload may also prefer a quieter setup. Lowering screen brightness, reducing background distractions, and completing account checks in a calm place can make the experience less demanding. A finance app does not need to be used in the noisiest part of a store. Preparing before leaving home is often the more inclusive choice.
A realistic everyday example
Imagine I am buying groceries after work. I am carrying bags, my attention is divided, and I do not want to pull out a wallet. I open Mercado Pago, scan the merchant’s QR code, inspect the amount, and confirm the payment. In that situation, the app saves handling and keeps the transaction digital.
Now change the conditions: the shop is crowded, the lighting creates glare, my phone is nearly out of battery, and I am using enlarged text. The same payment may require more time and more careful positioning. I would prepare the app before reaching the register, keep a backup payment method, and avoid confirming anything until the amount is readable. This is the difference between a feature being available and a task being genuinely easy.
That scenario also shows why accessibility is contextual. A person may manage the app comfortably at home but struggle at a checkout. Someone with limited hand movement may prefer it to cash yet still need help holding the phone. Someone with hearing loss may appreciate visual confirmation but need extra time to locate it. The best experience depends on the person, the device, and the surroundings.
Situational access and practical workflows
The app makes the most sense for people who want a digital account connected to payment tools and who regularly encounter merchants that accept QR payments. It is also attractive to users who want a card and a line of credit available within the same financial environment. The free price removes an obvious barrier to trying it, although financial products inside an app should still be judged by their terms and by the user’s ability to manage them responsibly.
One less obvious strength is the way it can reduce switching costs during a busy day. I can begin with a purchase, later check the account, and then review whether a card or credit option fits a separate need. Keeping those activities together helps me maintain a single routine. My advice is to separate “paying now” from “borrowing for later” mentally and financially, even if the interface places them close together.
Another useful workflow is preparing before going somewhere with uncertain connectivity. I would make sure the phone is charged, unlock access is working, and I know where to find the relevant account or card area. I would not assume that a QR payment will be possible in every setting merely because the app supports QR payments. The merchant, connection, device condition, and account status all affect the real experience.
People who receive help from a family member or support worker should establish a clear privacy routine. The helper can assist with reading, positioning, or navigating, but the account holder should confirm the amount and decide whether to proceed whenever possible. A shared phone can also create confusion between accounts, so I would check the active profile before making a payment rather than trusting the last screen left open.
Compared with cash, the app is faster when QR acceptance is available and removes the need to count change. Compared with a traditional bank app, its appeal is the combination of payments, a card, and credit-related tools in one digital environment. Compared with using only a physical card, it can reduce what I carry, but it makes the phone, battery, screen, and connection part of the payment chain.
That comparison reveals who should skip it. I would hesitate to recommend it as a primary financial tool to someone who rarely has reliable phone access, dislikes app-based account management, or needs a payment method that works independently of a charged smartphone. It may also be a poor fit for anyone who tends to accept credit offers impulsively or finds multiple financial choices confusing. In those cases, a simpler account or a physical payment method may be easier to control.
Remaining barriers I would not ignore
The biggest barrier is not necessarily the number of features; it is the consequence of making a mistake. A wrong recipient, an incorrect amount, or an unintended credit decision can matter more than a slightly awkward menu. I therefore value confirmation habits more than speed. I check the amount, identify the payment route, and avoid rushing because other people are waiting.
Privacy is another practical concern. A finance app should not be opened casually on a shared or public screen. Larger text can make reading easier while also making sensitive information more visible to people nearby. I would use it in a position where the display is not exposed, especially when checking account details or anything related to credit.
People with cognitive disabilities may benefit from a fixed routine: open the app, identify the intended task, read the amount, confirm the method, and verify the result. I would avoid exploring unfamiliar credit or card controls during a checkout. Exploration belongs at home, when there is time to understand what each option means and to stop without pressure.
Language and financial literacy can also affect access. The interface may be easy to tap but still difficult to interpret if terms are unfamiliar. A trusted person can help explain concepts, but I would not let anyone rush the account holder into accepting a financial product. Clear understanding matters more than completing the screen quickly.
Finally, I would keep records outside the immediate payment moment. A user who needs to track spending visually or with assistance may find it easier to review transactions at a scheduled time rather than after every purchase. That creates a calmer process and may reveal recurring spending patterns that are hard to notice during hurried checkouts.
My inclusive verdict
I see Mercado Pago as a capable choice for people who want QR payments, a digital account, a card, and access to a line of credit in one finance app. Its free availability, broad adoption, and support for Android devices from version 6.0 make it approachable for many users. The strongest experience comes from people who are comfortable managing money on a phone and who use merchants that support its payment flow.
From an accessibility perspective, I would call it useful but personal rather than universally effortless. It can reduce cash handling, simplify a wallet, and support visual payment routines, yet it still depends on the user’s phone, battery, connection, vision, dexterity, and understanding of financial choices. I would test the complete task with the person who will use it, not just assume that a successful installation means the app is accessible.
My practical recommendation is to start with low-risk actions, adjust the phone’s display and assistance settings, and establish a confirmation routine before relying on it for important payments. Keep a backup method, separate everyday spending from credit decisions, and protect the screen when using the app in public. The best reason to choose it is control in one place, not simply the promise of speed.
For me, that balance makes it worth considering, especially for everyday QR purchases and users who appreciate having several money tools together. I would choose a simpler or more traditional alternative when phone dependence, financial complexity, or sensory and motor barriers make independent confirmation unreliable. Used thoughtfully, it can be convenient; used hurriedly, it can make an important financial action feel easier than it really is.
As a finance app from Mercado Libre, it is free and carries an Everyone age rating. It was released on December 9, 2014, and its continued presence suggests a mature product rather than a temporary payment experiment. My final view is positive, with one condition: treat accessibility and financial safety as part of the setup, not as something to consider only after a problem occurs.
Pros
- Fast transfers and payments within the Mercado Pago ecosystem.
- Useful QR payments at participating stores and businesses.
- Debit card provides convenient access to your digital balance.
- Bill payments and mobile top-ups are available in one app.
- Transaction history makes it easy to monitor spending.
Cons
- Some features and fees vary depending on your country.
- Customer support response times may be inconsistent.
- Account verification can require personal documents and extra steps.
- Not every merchant accepts Mercado Pago payments.
- Advanced financial services may have eligibility requirements.
FAQs for Mercado Pago: cuenta digital
What is Mercado Pago: cuenta digital, and what can I use it for?
Mercado Pago: cuenta digital is a financial app that lets you manage money from your mobile device. Depending on your country and account eligibility, you can send and receive payments, pay bills, purchase online, recharge mobile credit, use a digital or physical card, and review your transaction history. Available features, limits, and fees may vary by location.
Is Mercado Pago: cuenta digital safe to use?
The app includes security measures such as login protection, transaction notifications, identity verification, and options for securing your account. However, users should still take precautions: download it only from the official Google Play Store or Apple App Store, never share verification codes or passwords, and enable every available security option. Mercado Pago will not eliminate all risks associated with digital payments.
Do I need a bank account or credit card to create a Mercado Pago account?
In many supported countries, you can open a Mercado Pago account without having a traditional bank account. Registration normally requires personal information and identity verification, and the exact requirements depend on local regulations. You may add money through supported methods such as bank transfers, cards, cash deposits, or affiliated locations, although not every funding option is available to every user.
Are there fees, limits, or requirements for using Mercado Pago?
Mercado Pago may apply different fees depending on the operation, country, payment method, account type, and whether you are using personal or business services. Some transfers, withdrawals, card transactions, or cash-out operations may have limits or charges. Before confirming a transaction, carefully review the amount, applicable commission, processing time, and daily or monthly limits shown in the app.
Can I use Mercado Pago: cuenta digital outside my country or on more than one device?
The service is designed primarily for the country where your account was registered, so international availability, currency support, card usage, and transfers can be restricted. You can usually sign in on another compatible device, but Mercado Pago may request additional verification for security reasons. If your phone is lost or replaced, use the official recovery process and contact support if access is blocked.

Mercado Pago: cuenta digital
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via app@mercadopago.com, visit http://www.mercadopago.com, or review their https://www.mercadopago.com/privacy/privacy-notice.










